(11-10-2025 08:01 AM)Eldonabe Wrote: (11-09-2025 01:49 PM)TripleA Wrote: Video here:
https://www.foxnews.com/video/6384870387112
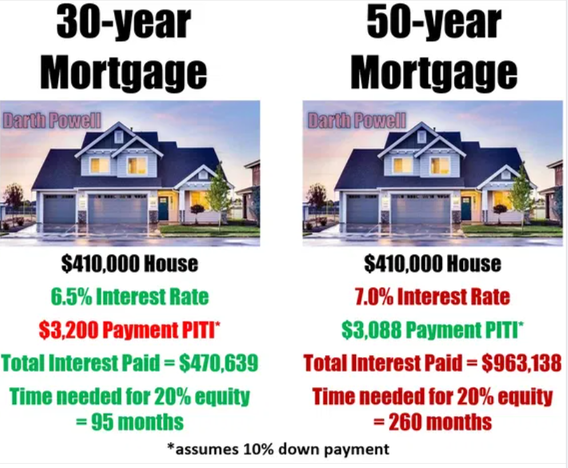
This only works if the rates are lower on the product.
320K Mortage (for a 400K home)
At 6% you are paying 1918.56 per month on just the loan (no tax ins etc). Over the life of the loan you are paying $50K more in interest than the actual principal on the loan.
Same thing except for 50 years. In the now, you are paying $1684 (appx $230 less) and now paying $370K more in interest than the original principal on the loan. You will not start building any reasonable equity through balance amortization for at least 20 years.
That is not a deal... without rate relief to go along with it.
Equity rarely is based on amortization, it’s based on leveraged return.
If you buy a $400,000 house and put $80,000 down, you have $80,000 in equity. If the home value increases 4% in year one, that’s $16,000 and represents a 20% return on equity, giving you $96,000 in equity. If your payment was $1,700 a month, you made $20,400 in payments. Minus the $16,000 in equity rise means your net occupancy cost was $4,400, or under $400 per month.
Within 5 years that property appreciation is outpacing your annually outlays. Your home equity is over $150,000, and that’s assuming below historical average appreciation rates. Compounding, leveraged returns are the quickest route to increasing wealth and home ownership is, by far, the safest and easiest vehicle for that. I put $20,000 down on a house in 1999 and have over $400,000 in home equity today and zero annual outlays for housing costs other than utilities and maintenance.
All that said, artificially inflating home ownership rates is a horrible practice. 100% financing is a horrible idea. Negative amortization mortgages are stupid. However, if someone has shown the discipline to save a down payment there should be a mechanism to get them in an appropriate home.

 /
Trump may propose a 50-year mortgage to incentivize young homebuyers